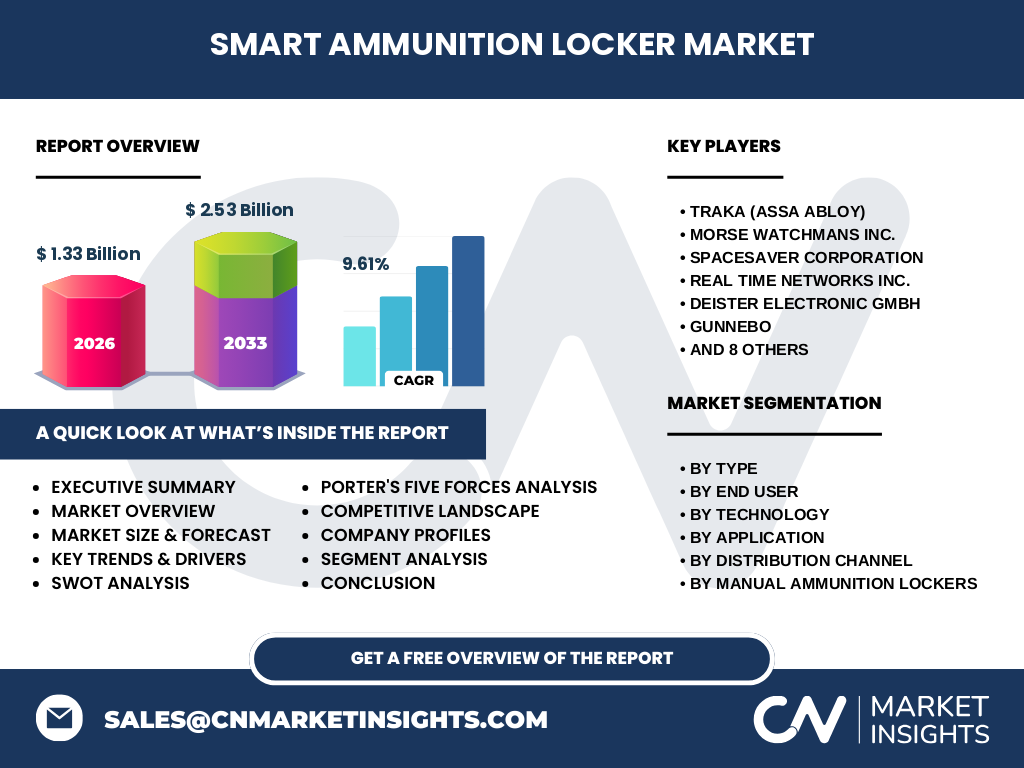
Market overview of the Smart Ammunition Locker Market
Our analysis indicates that the Smart Ammunition Locker Market is valued at $1.33 Billion in 2026. This sector encompasses advanced secure storage solutions integrating IoT, biometric authentication, and cloud-connected management to secure lethal assets. Industry significance centers on mitigating internal theft, ensuring compliance with ATF and DoD standards, and providing real-time audit trails for military and commercial armories.
Structural Growth Drivers and Market Restraints
The market is propelled by strict regulatory mandates from bodies like the FBI and OSHA requiring immutable access logs. Conversely, high upfront capital expenditure for network infrastructure and reluctance to adopt digital systems among traditional paramilitary units act as primary market restraints. Opportunities lie in retrofitting legacy vaults with Bluetooth-enabled conversion kits and biometric layers.
Emerging Trends in the Smart Ammunition Locker Market
A definitive shift toward edge computing and cloud-connected lockers is transforming armory management. Facilities are rapidly adopting biometric fingerprint lockers and RFID tracking to eliminate lost-key liabilities. Supply chain integration with enterprise resource planning software allows predictive replenishment of munitions based on live consumption analytics.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted component supply chains for semiconductors and hardened steel, stalling deployments across government installations. However, post-crisis focus on contactless infrastructure accelerated demand for touchless Personal Identification Number Code Enabled Lockers. The recovery trajectory has proven exceptionally robust, laying the groundwork for sustained expansion toward 2033.
Competitive Benchmarking and Market Concentration
Market concentration is moderately high, dominated by established security conglomerates and specialized IoT innovators. Key players like Traka (ASSA ABLOY) and Morse Watchmans Inc. leverage global distribution channels to dominate government contracts, while niche competitors such as WeaponTrackingIoT capture market share through proprietary software integrations and Modular Or Scalable Lockers.
Executive Summary of the Smart Ammunition Locker Market
The Smart Ammunition Locker Market industry trends reveal an aggressive expansion trajectory, scaling from $1.33 Billion in 2026 to $2.53 Billion by 2033 at a CAGR of 9.61%. Growth is heavily concentrated in government agencies and military defense sectors prioritizing automated chain-of-custody enforcement over traditional manual logbooks.
Market Forecast from 2027 to 2033
Based on our econometric modeling, the market will achieve a robust 9.61% CAGR over the forecast period, expanding from its 2026 baseline to reach $2.53 Billion by 2033. This acceleration is underpinned by rising geopolitical tensions, increased defense spending on base security modernization, and expanding commercial shooting range operations.
Segmentation Analysis of Storage Systems
Segmentation is evaluated across types, technologies, applications, and distribution channels. The Electronic Or Smart Lockers segment leads in value, driven by Biometric Fingerprint Lockers and Network-Connected Smart Lockers. Meanwhile, Rugged Or Tactical Lockers maintain critical adoption within frontline military units requiring weather-resistant and impact-resistant enclosures.
Regional Market Analysis and Geographic Performance
North America commands the largest revenue share, sustained by stringent federal defense procurement standards and high concentration of law enforcement agencies. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing market due to rapid military modernization initiatives in nations like India and Singapore, alongside expanding commercial security infrastructure.
In-Depth Regional Review
In North America, compliance with NIST and CJIS standards mandates high adoption of network-connected systems. Europe exhibits steady demand driven by NATO standardization directives. In contrast, the Middle East and Africa focus heavily on Heavy Duty Reinforced Lockers deployed in harsh desert environments for border security applications.
Company Profiles and Strategic Positioning
Industry leaders employ distinct strategies to capture market share. Spacesaver Corporation and McMurray Stern leverage heavy mechanical engineering expertise for robust physical storage, whereas deister electronic GmbH and Real Time Networks Inc. compete on software-driven intelligence, offering seamless RFID and cloud-managed oversight.
Porter's Five Forces Analysis
Competitive rivalry is intense among established security brands, while the threat of new entrants remains moderate due to strict defense certification hurdles. Bargaining power of buyers is high among large government agencies capable of demanding bespoke integrations, whereas supplier power is concentrated in specialized biometric sensor and alloy manufacturers.
SWOT Analysis of the Industry
Key strengths include high-margin software integration and bulletproof audit reliability. Weaknesses involve complex installation requirements. Opportunities abound in expanding Commercial Or Industrial shooting facilities. Threats include firmware vulnerabilities and potential supply chain bottlenecks for high-grade encryption microchips.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction—primarily ballistic steel and aluminum. Component manufacturers fabricate structural housings and integrate biometric sensors. System integrators like Gunnebo and Ecos Systems assemble the units, applying proprietary firmware before deployment to end-users across defense and commercial sectors.
Investment Insights and Strategic Recommendations
Investors should target startups specializing in Cloud Connected Lockers and decentralized multi-user access control. Strategic M&A activity is expected as physical security heavyweights acquire software-first innovators to secure proprietary encryption algorithms and expand their footprint in emergency preparedness markets.
Conclusion and Key Takeaways
The transition from mechanical keys to interconnected smart storage is irreversible. With the market reaching $2.53 Billion by 2033, stakeholders must prioritize software scalability, robust cybersecurity compliance, and modular hardware designs to capture high-value government and tactical contracts.
Research Methodology
Our findings are triangulated through a rigorous mix of primary stakeholder interviews with chief security officers and military procurement heads, combined with secondary data from trade registries, macroeconomic indicators, and regulatory filings from entities like the Department of Defense.
Scope of the Report
This report covers global market dynamics for the Smart Ammunition Locker Market analysis across five core geographical regions and five primary segmentation layers from 2026 through 2033. Exclusions include legacy un-networked residential gun safes not equipped with electronic tracking or telemetry.
Recent Developments in the Industry
Recent market activity highlights strategic partnerships between IoT software providers and physical security manufacturers. Firms like Videx (CyberLock) have launched advanced keyless integration protocols, while companies such as SWS Inntech SDN BHD and Locker Solutions expand their geographic reach through localized distribution agreements targeting emerging defense markets.